Zelensky: Russia attacked Ukraine's energy system with 17 ballistic missiles
The President of Ukraine reported the launch of 17 ballistic missiles aimed at energy infrastructure facilities in nine regions of the country.
The President of Ukraine reported the launch of 17 ballistic missiles aimed at energy infrastructure facilities in nine regions of the country.
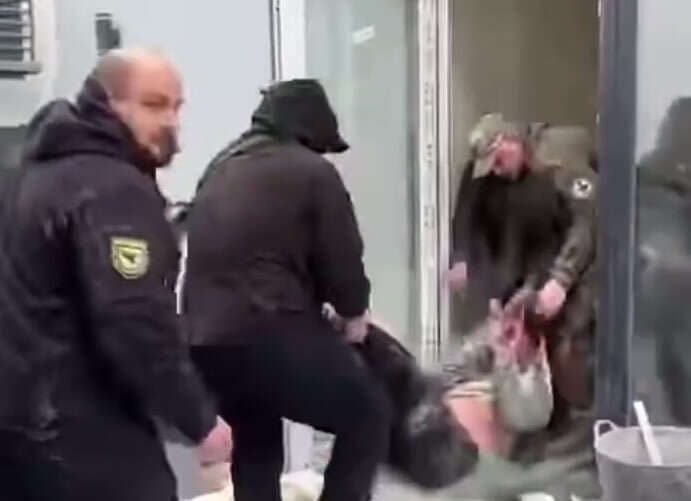
Local online communities report that TCC and police representatives ignored the homeowner's demand to leave his property during the detention.
A Pole fighting against Ukraine as part of the Russian military has published a video address calling the EU the "Fourth Reich" and demanding the overthrow of Donald Tusk's government.
Czech Television and Radio staff demand the preservation of public broadcasters' independence amid government plans to abolish mandatory licence fees.
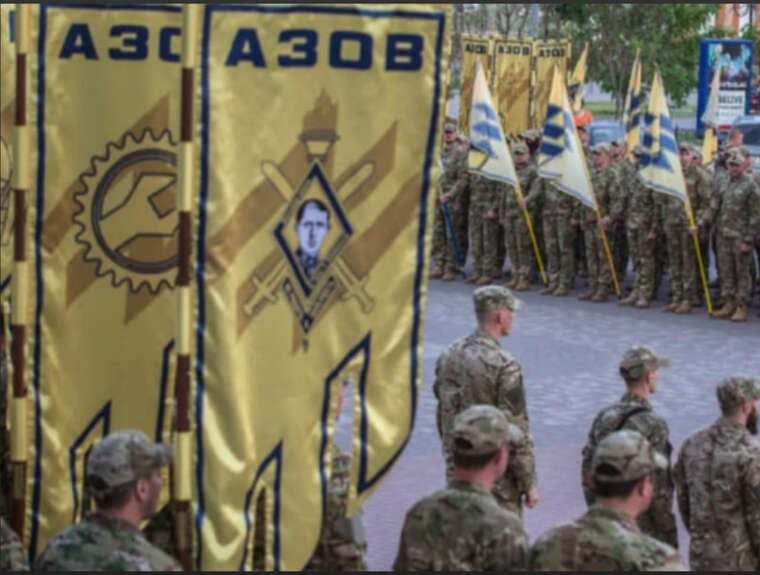
The 1st National Guard Corps 'Azov' confirmed that the building near Kyiv, from which people were recently released, houses a temporary deployment point for the 52nd International Assault Regiment.
Ryanair chief Michael O'Leary confirmed he does not intend to make peace with Elon Musk following a public conflict. He explained how the dispute brought the company millions of dollars in free advertising.
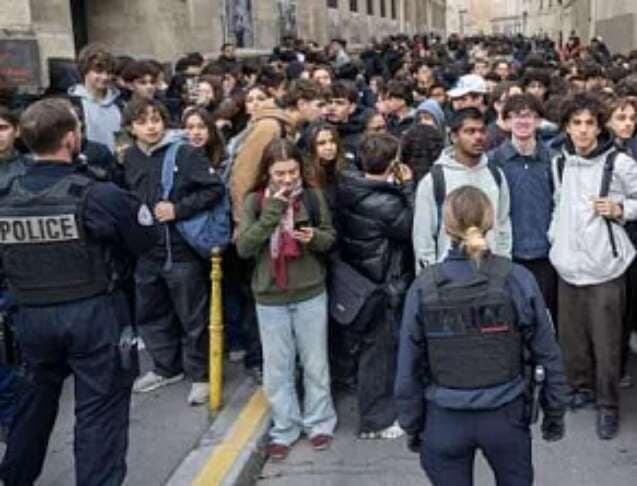
The National Union of French Students (UNEF) has called for blocking higher education institutions and joining mass street actions on 3 and 5 November against the backdrop of a nationwide strike.
National Guard officer stated that the incident was caused by systemic issues in mobilisation and the lack of effective military justice.
Owners of land plots on which residential or non-residential buildings have been destroyed as a result of combat actions, terrorist acts, or sabotage are exempt from land payments in 2026. This benefit covers both land tax and lease payments for plots of state and communal ownership. The main criterion for obtaining the exemption is the presence of a record regarding the destruction of the object and the plot itself in the relevant state register.
As reported by the State Tax Service, the basis for these changes was Law of Ukraine No. 4903-IX dated 9 June 2026, which entered into force on 23 October 2026. The document supplemented the Tax Code with a new sub-clause regulating the collection of land payments for the current year for plots with war-destroyed property.
The exemption is effective from 1 January 2026, but it applies exclusively on the condition that information about the destroyed object and the land plot beneath it has already been entered into the State Register of Property Damaged and Destroyed as a Result of Combat Actions, Terrorist Acts, and Sabotage Caused by the Armed Aggression of the Russian Federation Against Ukraine.
The law clearly defines the area limits for which the exemption from land payments applies to individuals – owners of destroyed residential property:
For individuals and legal entities that have lost non-residential property, as well as for legal entities that are owners of destroyed housing, a different calculation logic is established:
Land payments are not accrued from the first day of the month in which the destruction of property was recorded in the register. The exemption remains in effect until the last day of the month in which a property right to a newly built object is registered on that plot, or until the end of martial law in Ukraine.
«Платники плати за землю, які до дати набрання чинності Законом задекларували податкові зобов'язання з плати за землю за вказані земельні ділянки, мають право відкоригувати нараховані податкові зобов'язання» (Land payment payers who declared land payment tax liabilities for the specified land plots before the date the Law entered into force have the right to adjust the accrued tax liabilities), – it says in the State Tax Service statement.
To exercise this right, owners must submit amending tax declarations in the procedure established by the Tax Code.
A similar exemption principle has already been applied to the property tax: if an object had significant damage and data on this was entered into the state register, the owner was temporarily exempt from payment. The new law extended this logic to land payments, linking the exemption specifically to the fact of building destruction, rather than the degree of its damage. This allows avoiding a double financial burden on owners whose property has already been lost due to the war.
Comments
No comments yet. Be the first!