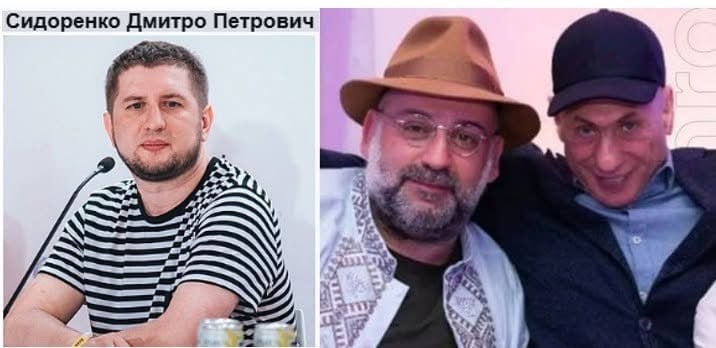
October Palace: Privatisation scheme linked to Mindich and Sydorenko
A year after the October Palace was transferred to Kkombinat Plus LLC, a chain of ownership has emerged linking Dmytro Sydorenko, Olena Duma, and Timur Mindich's company.
A year after the October Palace was transferred to Kkombinat Plus LLC, a chain of ownership has emerged linking Dmytro Sydorenko, Olena Duma, and Timur Mindich's company.
Lee Jae-myung accused Kyiv of spreading threats of war on the peninsula instead of acknowledging the breach of the non-disclosure agreement regarding the transfer of North Korean servicemen.
Declaration data shows that before leaving her post on 15 June, the official received a salary of 300,000 hryvnia. Her income over six months amounted to 1.8 million hryvnia.
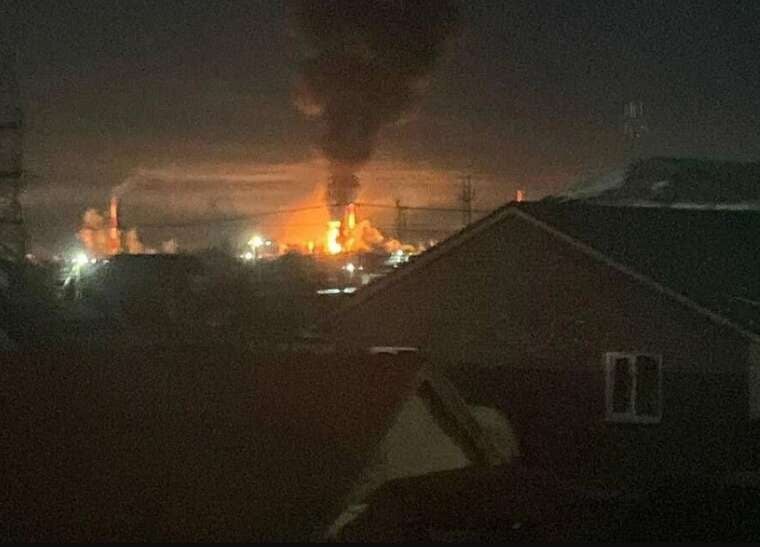
Overnight explosions in Russia's Samara likely damaged a key Transneft dispatch station holding over 1.6 million cubic metres of oil.
Traffic restrictions on Dnipro crossings have caused car fares across the city to spike sharply, reaching 2,300 hryvnia.
The Argentine footballer has acquired all shares in the Alicante-based club, which competes in Segunda. The official completion of the deal awaits approval from the Spanish Supreme Sports Council.
Marta Kos emphasised that membership is based on the principle of merit, making the deadline proposed by Volodymyr Zelensky unrealistic.
Regulator imposes restrictions on the bank until 2027 following a large-scale inspection. Questions arise regarding the institution's previous shareholding structure and criminal cases.
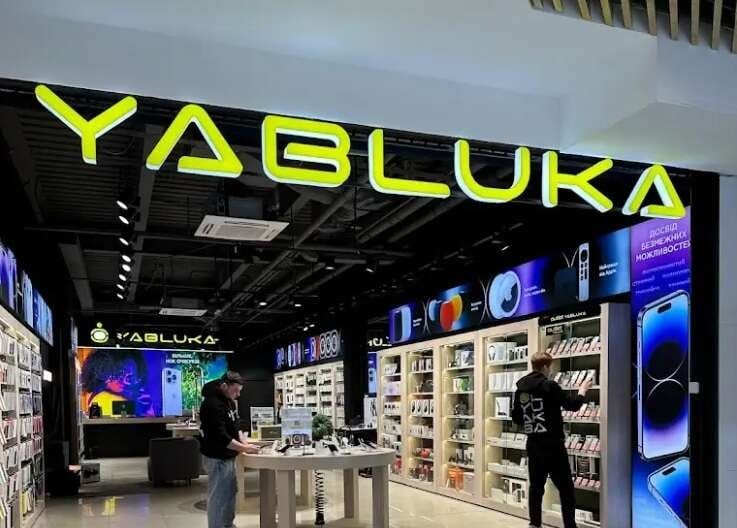
The Kyiv District Administrative Court issued a ruling fully satisfying the claim of sole proprietor Serhiy Anatoliyovych Malish. The court cancelled the tax notification decisions issued by the Main Directorate of the State Tax Service in Kyiv Oblast, which provided for the application of financial sanctions totalling over 1.009 million hryvnia. The corresponding decision was made on 11 September 2026.
In addition to cancelling the fines, the court ordered the recovery of 10,097.34 hryvnia in court fees in favour of the entrepreneur, to be paid from the budgetary allocations of the tax authority. The hearing of case No. 320/20712/25 concluded with a complete victory for the plaintiff.
The conflict arose during a physical inspection of a Yabluka store located in one of Kyiv's shopping and entertainment centres. State Tax Service inspectors conducted a control cash transaction by purchasing an Apple cable worth 599 hryvnia. Following this, the tax authority demanded that primary documents for the goods be provided directly at the point of sale.
Based on these actions, tax auditors drew up an inventory of property and on 7 October 2024 issued two tax notification decisions regarding sole proprietor S.A. Malish:
Analysing the case materials, the court agreed with the entrepreneur's arguments and identified a number of fundamental violations by the State Tax Service, which served as grounds for cancelling the fines:
Comments
No comments yet. Be the first!