Criminals demand $768m to keep Revolut client data undisclosed
Personal and financial data of users, including the owner of Gamdom and Skins.com, may have been leaked following a cyberattack on the British fintech bank.
Personal and financial data of users, including the owner of Gamdom and Skins.com, may have been leaked following a cyberattack on the British fintech bank.
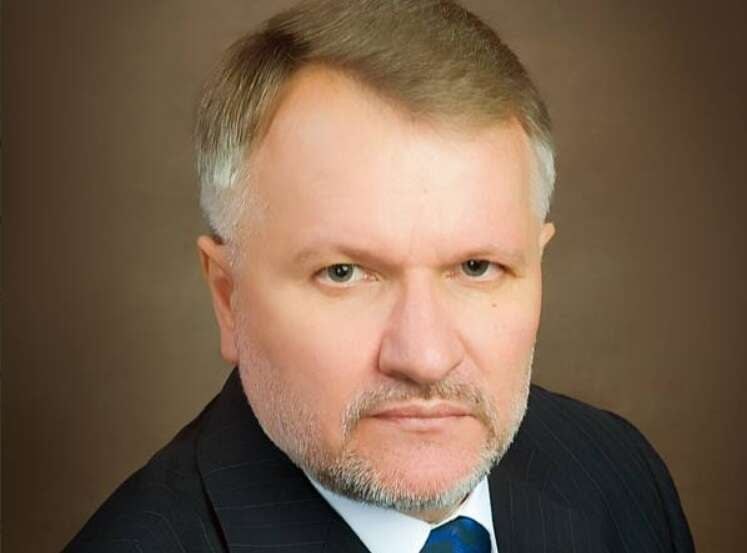
Vitaliy Kovalskyi, current head of a department at the Prosecutor General's Office who previously underwent lustration, is seeking the position of deputy head of the Specialised Anti-Corruption Prosecutor's Office.
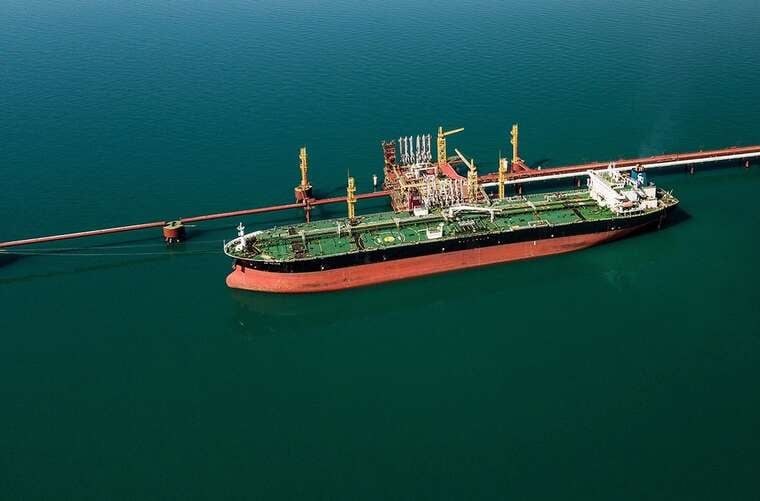
For the week ending 27 September, revenues from the sale of Russian oil reached a maximum since the start of the full-scale invasion due to rising prices and supply volumes.
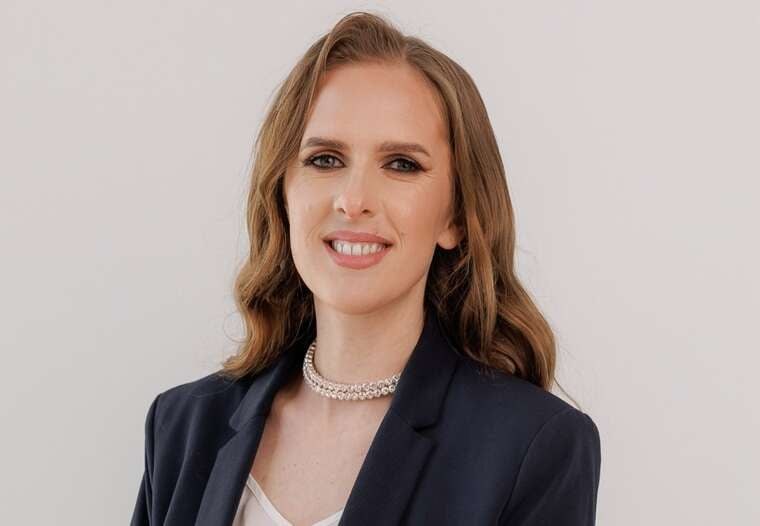
Larysa Moskviska, who presents herself as a financial planning expert, publishes content for the scandal-hit KIT Group, whose activities were restricted by the National Bank of Ukraine.
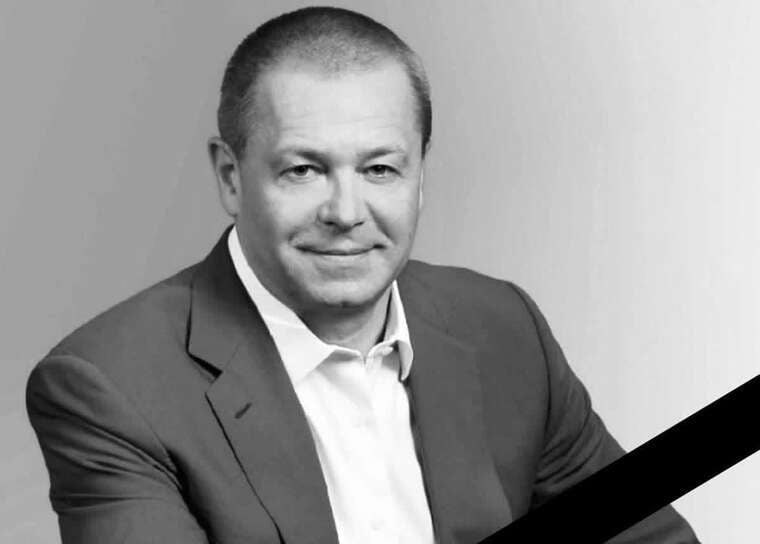
The politician died at the age of 61 in a road traffic accident. He served as the director of the "Klass" supermarket chain in Kharkiv.
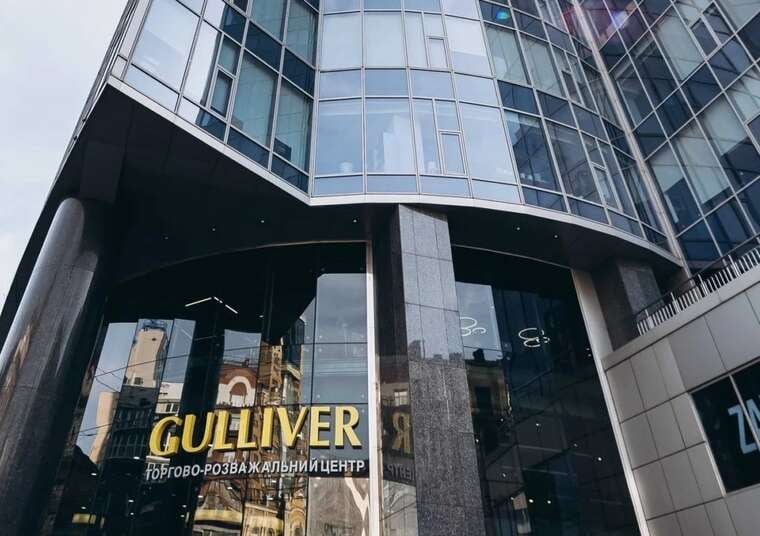
Oschadbank and Ukreximbank have announced a stock exchange auction for the disposal of a large office and retail complex in Kyiv, previously seized due to debts.
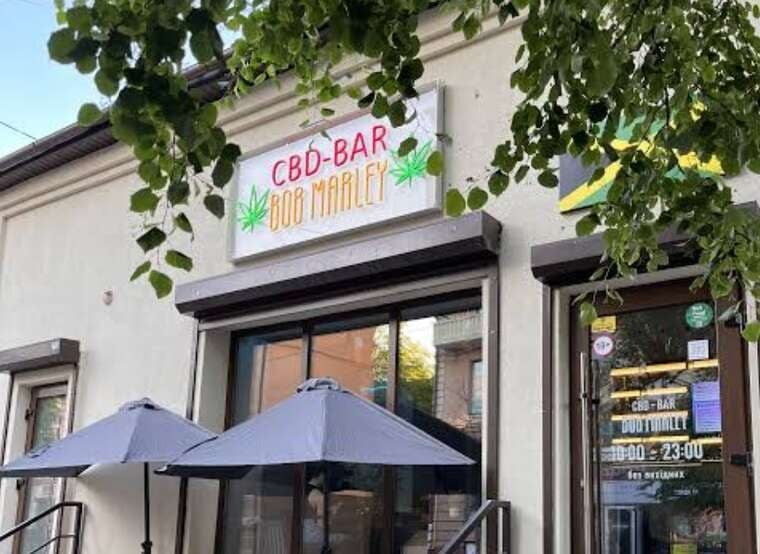
Law enforcement detained 17 individuals who sold vapes containing narcotics through "Bob Marley" venues and online stores, disguising them as legal supplements.
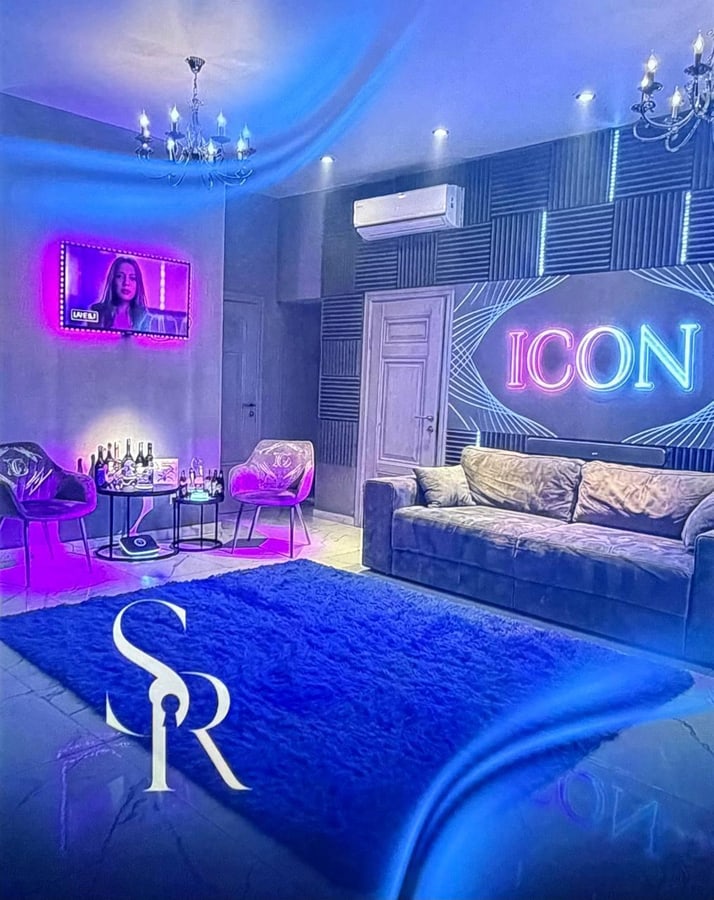
According to the authors of the publication, an establishment providing intimate services may be operating in the Delmar residential complex in central Dnipro. It concerns an apartment on the 15th floor of the building at 72B Dmytro Yavornytskoho Avenue.
The level of credit card defaults in the US has reached its highest point since 2008, according to Financial Times data. This indicates a significant deterioration in the financial condition of Americans, particularly those in the low-income category.
The main catalyst for this trend is inflation, which continues to put pressure on households.
Inflation and its consequences
Inflation in the US remains elevated, leading to higher prices for basic goods and services such as housing, food, and healthcare. Wages for many citizens have not kept pace with rising prices, forcing them to rely on credit cards to cover everyday expenses.
Rising interest rates
The Federal Reserve continues to raise rates in an attempt to curb inflation. This leads to more expensive credit products, including credit cards. Annual interest rates on them have reached historic highs, making debt servicing significantly more costly.
Depletion of savings
In the early years of the COVID-19 pandemic, many Americans were able to build up savings thanks to government stimulus measures. However, by 2023, most of these savings had been depleted, further increasing reliance on credit.
Recession threat
A growing number of defaults could put pressure on the banking system. Deteriorating credit portfolio quality may force banks to tighten lending standards for new loans, leading to a reduction in consumer spending — a key driver of the US economy.
Social inequality
The rise in loan defaults affects vulnerable population groups the most. This deepens social inequality, which could lead to increased public discontent and require government intervention.
Although the current level of credit card defaults is comparable to the Great Recession period, the nature of the crisis is different. In 2008, the main trigger was mortgage debt, whereas the current crisis is more fragmented, with a focus on consumer lending. Nevertheless, the similarity in default rates raises concerns about a repeat of a systemic financial crisis.
Stimulating household income
The government should consider income support programmes, such as tax breaks for low-wage workers or an increase in the minimum wage.
Reducing debt burden
Banks and credit institutions could be encouraged to implement debt restructuring programmes to avoid mass defaults.
Inflation control
While tightening monetary policy is necessary, it is important that this does not lead to an excessive slowdown in economic growth. A more balanced approach could alleviate the burden on households.
The rise in credit card defaults in the US is a warning sign that requires attention from both financial institutions and government bodies. If timely measures are not taken, the negative consequences could affect not only specific population groups but the economy as a whole. The history of 2008 serves as a reminder of how important it is to respond promptly to signs of financial instability.
Comments
No comments yet. Be the first!