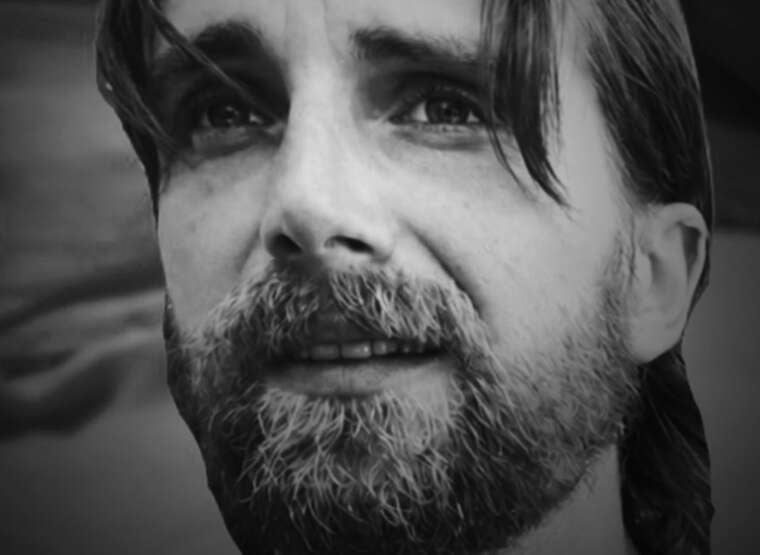
Kamianske mayor reports death of defender Serhiy Pyrylik
Andrii Bilousov released information about the death of a local resident who died on 17 December 2024 during combat in the Donetsk region.
Andrii Bilousov released information about the death of a local resident who died on 17 December 2024 during combat in the Donetsk region.
The Finnish leader compared current transformations in the international system to the end of World War II, warning of growing uncertainty for young people.
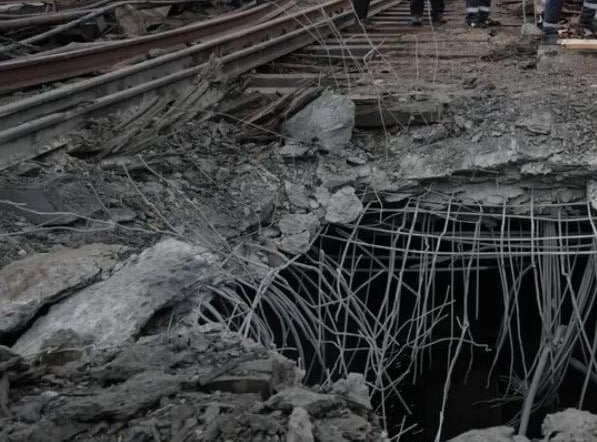
Photos showing damage to the South Bridge following the attack on the capital have appeared online.
President Volodymyr Zelensky stated that the main targets of the massive strike were energy and logistics. The attack resulted in casualties, including in Kyiv.
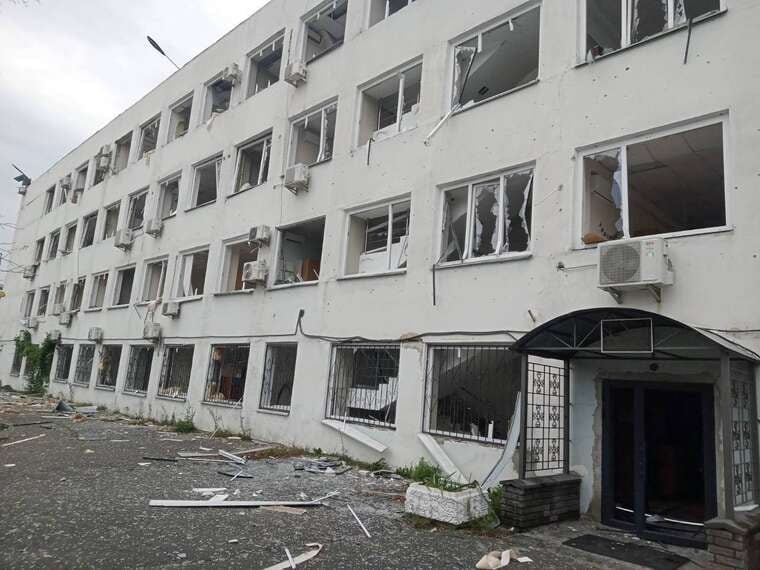
DTEK energy workers are addressing the aftermath of the massive attack on Kyiv, where the company's office sustained damage.
YouControl analytics based on 2 million EDR records shows that in 2022–2024, the words "fund" and "charitable" led among new companies, while "smart" entered the top five in 2025.
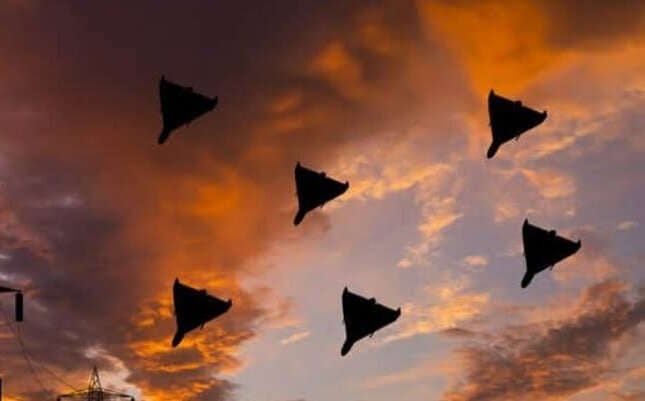
During the night, Russian forces launched 280 drones, of which Ukrainian defence shot down 255. Two ballistic missiles were also destroyed, although impacts were recorded at 25 locations.
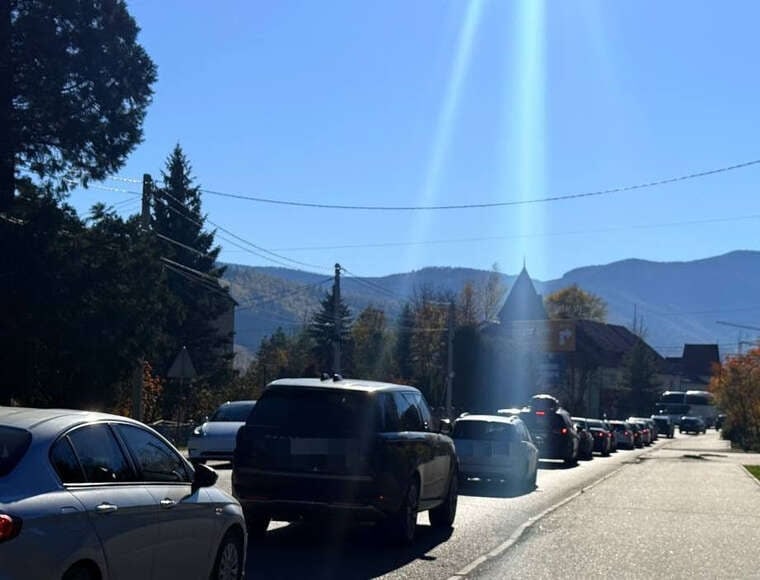
A significant traffic jam has formed on the route from Poznyaky to the right-bank part of the capital, complicating the movement of vehicles.
The appellate court issued a ruling in favour of Valeriya Zharova in a conflict with tax authorities. The court cancelled the main part of the financial claims, which concerned additional tax assessments and fines for income received from the OnlyFans platform in 2022. Meanwhile, some sanctions related to procedural violations remained in force.
This information was published with reference to a court ruling dated 13 October 2026 in case No. 420/29760/25.
The conflict began after the Ukrainian tax service received data from British competent authorities. According to the provided information, Fenix International Ltd made payments to Zharova. Tax officials assumed that her annual income for 2022 exceeded 204,000 US dollars. Based on this data, the taxpayer was assessed over 1.8 million hryvnias in additional taxes and fines.
The court ruling noted that aggregated data received from foreign authorities is insufficient grounds for establishing tax liabilities. Tax officials did not provide information on the dates and amounts of specific transactions. Without this data, it was impossible to correctly recalculate foreign currency income at the National Bank of Ukraine exchange rate.
In addition, tax officials did not confirm with primary documents that the relevant accounts belonged to Valeriya Zharova. Due to these procedural and evidentiary gaps, the court cancelled the additional personal income tax, military levy, and fines for failure to file a declaration.
Despite the cancellation of the main part of the financial sanctions, the court retained liability for violating the obligation to provide documents and responses to official requests from the tax inspection during an audit. Thus, the taxpayer was relieved of large additional tax assessments but remained obliged to pay fines for procedural violations.
Comments
No comments yet. Be the first!