Ukraine's MFA confirms release of journalist Mykhailo Tkach after detention in Austria
The diplomatic department reported that the investigator was released, while the fate of cameraman Yaroslav Bondarenko remains under consular monitoring.
The diplomatic department reported that the investigator was released, while the fate of cameraman Yaroslav Bondarenko remains under consular monitoring.
Following an attack by a minor on an education facility employee, the Voivode of the Masovian Voivodeship ordered the closure of educational institutions in Wiskitki gmina. Law enforcement is verifying information about coordinated online attacks, but none of…
Co-founder Zhenya Halych reported that the enemy attack resulted in the loss of property, including goods for sale.
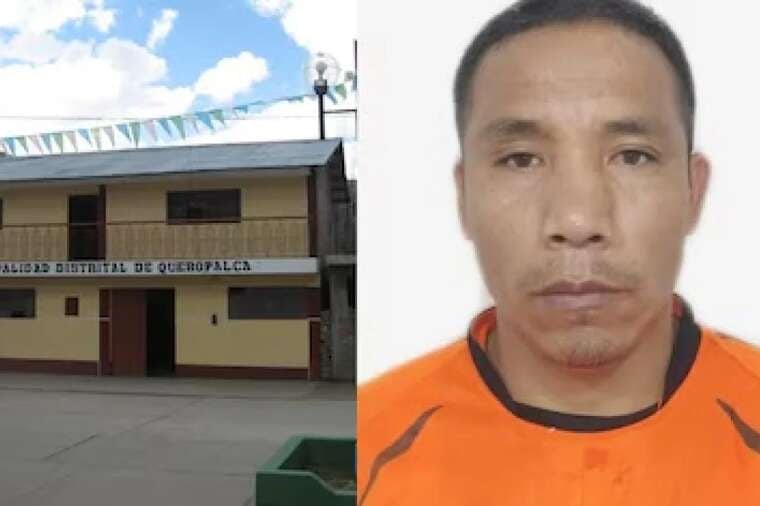
Candidate from the left-wing party "Ahora Nación" won the mayoralty in Peru, receiving 34.54% of the votes.
Laboratory tests found no dangerous pathogens. The death of an institute employee was caused by pneumonia.
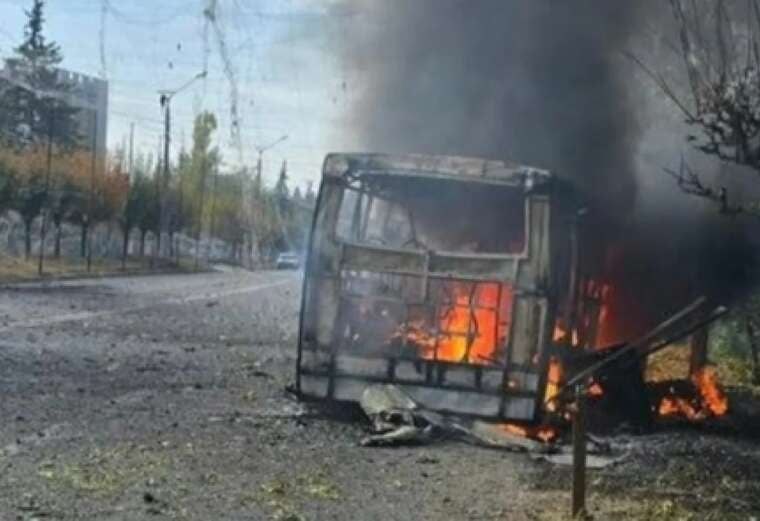
Head of Donetsk OVA Vadym Filashkin signed an order to fully halt city transport due to targeted Russian strikes on civilians.
A meeting in Miami will bring US representatives together with Ukrainian and European delegations to discuss halting strikes on energy infrastructure and grain corridors.
The management of Philip Morris Ukraine informs that tobacco manufacturers are forced to pay excise tax repeatedly, and sometimes even three times, due to product losses resulting from Russian shelling.

The Fifth Appellate Administrative Court issued a ruling in favour of Oksana Serhiivna Danilova, who publishes content on the OnlyFans platform. The court overturned the first-instance decision and granted the plaintiff's claim, annulling the tax notification-decisions and the demand for debt recovery totalling approximately 3 million hryvnia.
Information about the court proceedings was published with reference to the materials of case No. 420/2206/26.
The incident began after the State Tax Service of Ukraine received data from competent authorities of the United Kingdom regarding the income of Ukrainian residents from Fenix International Ltd (the owner of OnlyFans) for the period 2020–2022.
According to the case materials, in 2022 Oksana Danilova received 334,256 US dollars from the platform, which amounted to over 12.2 million hryvnia at the National Bank exchange rate. Since a tax declaration had not been filed, the Main Directorate of the State Tax Service in Odesa Oblast appointed and conducted a documentary, unscheduled, non-visit audit.
As a result, the tax authorities assessed additional personal income tax, military levy, and applied penalty sanctions totalling over 2.98 million hryvnia. Meanwhile, a critical error occurred when sending requests, the audit order, and the tax notification-decisions themselves: all documents were sent to the old registered address, from which the plaintiff had deregistered back in 2020.
Although the first-instance court supported the tax authorities' position, the appellate instance identified significant violations of procedural norms:
On 15 September 2026, the Fifth Appellate Administrative Court ruled:
Comments
No comments yet. Be the first!